Anthropic's S-1: a $974 million operating profit in Q2 2026
 Allen Yan · · 6 min read
Contents
Anthropic, PBC filed its registration statement with the SEC at 9:00 a.m. Eastern on October 26, 2026. The S-1 asks to list Class A shares on the Nasdaq Global Select Market under the ticker ANT. The price range and the share count are still blank.
Until today the numbers came from people who had seen the confidential draft. I covered that version in September, from Reuters' reading of it. Every figure below is from the filed document, and every ratio is my arithmetic on it.
Today at a glance:
- Revenue: $11.6 billion in the second quarter of 2026, 14.7× the same quarter a year earlier.
- Operating result: $974 million of operating income in that quarter. It is the first profitable quarter in the S-1's quarterly table.
- Net loss: $80.7 billion for the first half. $72.4 billion of it is a change in the fair value of convertible notes and SAFEs.
- Cash: $131.7 billion in cash and short-term investments on June 30, 2026.
- Control: a trust elects most of the board, and a founders' LLC holds one share with 50.1% of the votes.
Revenue: $11.6 billion in Q2 2026, up 144% Q/Q
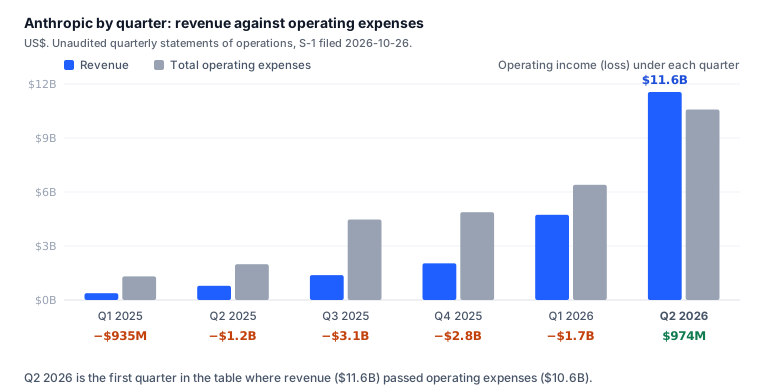
- Q2 2026 revenue +1,368% Y/Y and +144% Q/Q to $11,555 million (from $787 million and $4,731 million).
- First-half revenue $16,286 million, against $1,163 million a year earlier. That is 14.0×.
- Full-year revenue $41 million in 2023, $386 million in 2024, $4,585 million in 2025.
There is no consensus to beat. The company has never reported publicly, so this section has growth figures and nothing else.
Key developments:
- Customers spending $100,000 or more a year: more than 950 on September 30, 2025, and more than 11,900 a year later. The count is on a trailing-twelve-month (TTM) basis.
- Net revenue retention of about 900% as of September 30, 2026. Existing customers spend roughly nine times what they spent a year before.
- New models carry the revenue. Versions released in the six months to September 30, 2026 made up over 80% of third-quarter revenue.
- Concentration is falling. Customers outside the top five were about 79% of third-quarter revenue, up from about 64% in the first quarter. One customer was still 11% of first-half revenue.
- Takeaways: the S-1 gives no third-quarter revenue figure. It says only that third-quarter revenue was 86 times the fourth quarter of 2024.
Operating income: positive in Q2 2026, at an 8.4% margin
- Q2 2026 operating income $974 million, after a $1,667 million loss in the first quarter. Margin 8.4% ($974M ÷ $11,555M).
- First-half operating loss $693 million. The S-1's own adjusted operating income, which leaves out stock-based compensation, non-cash charitable contributions and the Bartz settlement, was $1,618 million, a 10% margin.
- Operating cash flow +$3,929 million in the first half, against −$1,513 million a year earlier.
Key developments:
- Compute got cheaper per dollar of revenue. Compute and infrastructure cost $5,558 million in Q2 2026, 48% of revenue. A year earlier it was $1,390 million, 177% of revenue.
- Selling got expensive. Sales, marketing and partnerships rose from $96 million in Q2 2025 to $2,135 million, 22× in a year.
- Stock-based compensation was $2.2 billion in the first half, up from $286 million.
- The 2025 loss had a one-off. The $1.5 billion Bartz settlement (the authors' copyright class action) sits in the third quarter of 2025.
- Headcount grew slower than revenue. From December 31, 2024 to September 30, 2026, headcount grew more than five times. Over the same stretch, quarterly revenue grew 86 times.
- Claude writes most of the code. Over 90% of contributions to Anthropic's codebase in September 2026 were written by Claude. Daily code volume per engineer in the third quarter was more than 45 times the 2024 average.
Net loss: $80.7 billion, and $72.4 billion of it is a fair-value change
Anthropic raised money through convertible notes and SAFEs, and records them at fair value. When the company's valuation rises, the instruments are worth more, and the increase is booked as a loss. The S-1 says so in a footnote to the summary table.
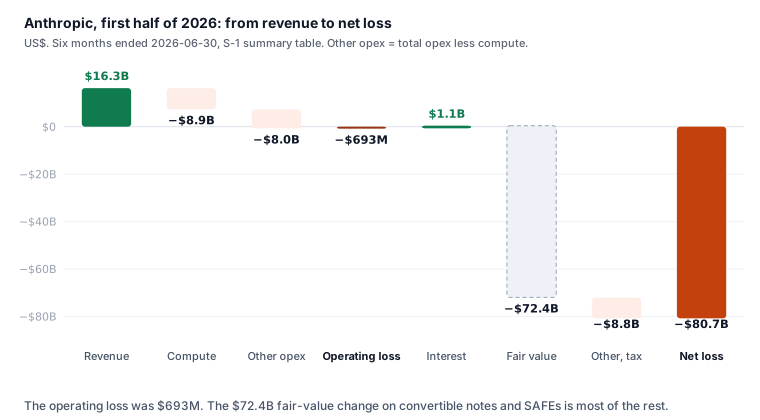
- First-half net loss $80,748 million. The fair-value change is $72,388 million of it, about 90% ($72,388M ÷ $80,748M).
- Other expense of $8,757 million is a separate line. The summary table does not explain it.
- Accumulated deficit $132.9 billion on June 30, 2026.
The notes the S-1 names are Amazon's. Amazon Web Services bought them under two agreements, dated September 19, 2023 and November 22, 2024, and they convert into non-voting Class N shares.
The pro forma column, which shows the loss as if the notes had converted on January 1, 2025, is still blank. The S-1 has the notes converting at the offering.
Cash and commitments: $131.7 billion in hand, $54.6 billion committed at 2025 year end
Financing brought in $110.8 billion in the first half. Investing used $17.2 billion.
Non-cancelable purchase commitments longer than a year, mostly cloud hosting, came to $54.6 billion on December 31, 2025. The S-1 lists them by year:
| Year | US$ millions |
|---|---|
| 2026 | 7,059 |
| 2027 | 11,128 |
| 2028 | 10,832 |
| 2029 | 8,304 |
| 2030 | 5,428 |
| After 2030 | 11,808 |
| Total | 54,559 |
That figure is dated before the 2026 deals. The draft coverage put commitments at $518 billion across six partners, and the filing does not confirm it: the total "as of and subsequent to September 30, 2026" is blank, and so is the run-rate revenue as of October 31.
One of those deals is in the S-1. In March 2026 Anthropic signed an equipment lease with Broadcom for AI accelerators. To pay for it, Anthropic may issue up to $42.0 billion of convertible notes to Broadcom or a financial partner Broadcom designates.
Governance: a trust, a founders' share and five share classes
- Class A, the shares on offer: one vote each.
- Class N, held mostly by strategic partners: no vote, and it converts to Class A when sold to an unaffiliated buyer.
- Class T, held by the Long-Term Benefit Trust: no economic rights, but it elects the Class T directors, a majority of the board.
- Class F, one share held by an LLC of the seven co-founders: 50.1% of the votes on everything else, including the other directors.
- Class E, for employees other than the co-founders: votes on a few limited matters only.
One large Class N holder is the company's own subsidiary. Anthropic issued 846,840,960 Class N shares to the Anthropic Public Benefit Fund, a wholly owned subsidiary. That is 5% of fully diluted shares as of June 30, 2026, counting the Amazon notes as converted, which puts the fully diluted count near 16.9 billion (846,840,960 ÷ 0.05). The board may add up to 2% more each time the share price rises 50% above the previous milestone, starting from the IPO price. The co-founders have each pledged 80% of their equity in Anthropic to philanthropy.
Anthropic is a Delaware public benefit corporation, so the board must weigh shareholders' money against its stated purpose. Goldman Sachs and Morgan Stanley represent the underwriters, with J.P. Morgan and BofA Securities also listed.
The figures the press reported from the draft held up: first-half revenue of $16.3 billion, 2025 revenue of $4.6 billion, a 2025 net loss of $42.0 billion. What the filing adds is the quarterly table, and the open question is the third quarter's revenue, which only an amendment will show.
Sources and data
- Anthropic, PBC, Form S-1, filed 2026-10-26 (SEC EDGAR, CIK 2130357, accession 0001628280-26-067168): summary consolidated financial data, quarterly results of operations, cash flows, the concentration note (F-16), the purchase commitments note, the indebtedness risk factor (Amazon notes, Broadcom lease), the public benefit section and the governance summary.
- SweetValueLab, Anthropic's IPO prospectus, as reported, September 2026: the draft figures as Reuters read them.
The weekly
The week's 13F filings, insider trades and earnings, plus new research on the site. One email a week, no account.
More posts
- Alphabet Q3 2026: Cloud +103%, free cash flow −$9.1B
- GE Vernova Q3 2026: $29B of orders, paid for in advance
- SoFi Q3 2026: revenue +44%, a $0.90 EPS outlook for 2027
- Coca-Cola Q3 2026: volume +5%, EPS guidance raised to 11%
- Tesla–SpaceX merger: the exchange ratio, valued part by part
- SpaceX Q3 2026: revenue +161%, the valuation moves $2
- Why do stocks fall after beating earnings?
- Why Goldman, Citi, J&J and ASML stocks fell after earnings
- Anthropic's $16.8B quarter: the investor day numbers
- What is a DCF? What a corner shop is worth
- How the 10-year Treasury moves every valuation on this site
- Delta vs United by the numbers
- Anthropic's IPO prospectus: the numbers behind the $42B loss
- Who actually owns this stock: how to read a 13F
- How to read a market sentiment gauge
- Market breadth: the index can rise while most stocks fall
- How we value a stock: twelve models, one number
- Where the numbers come from: filings, point in time
- Tesla, taken apart: a sum of the parts in three scenarios
- How to read a reverse DCF: the growth a stock price implies
- How to value a bank: P/TBV, ROTCE and the line
- How to value a REIT: FFO, P/FFO and the yield spread
- How to value a software company: Rule of 40 and SBC
- Total return vs price return: what a stock chart leaves out
- What a backtest cannot tell you