Coca-Cola Q3 2026: volume +5%, EPS guidance raised to 11%
 Allen Yan · · 5 min read
Contents
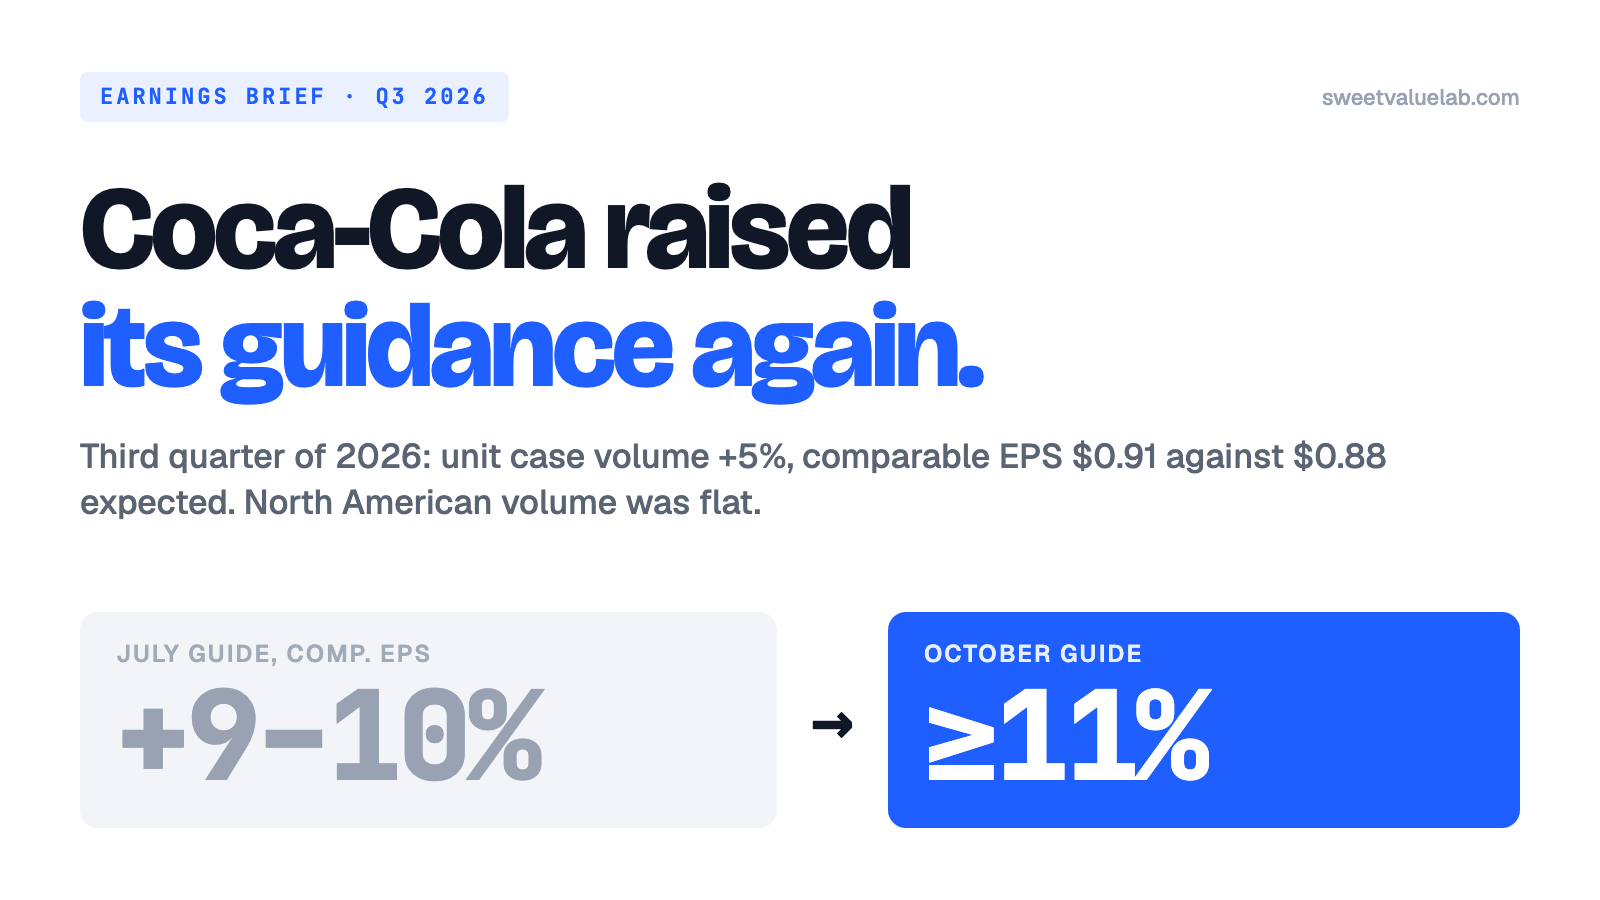
Coca-Cola reported its third quarter of 2026 before the open on October 27 and raised its full-year guidance for the second report running. CEO Henrique Braun said the results gave the company "confidence in our updated full year guidance". Revenue came in at $13.38 billion, the same figure to the million as the second quarter.
Everything below comes from the earnings release (8-K exhibit, filed 2026-10-27). I use FMP's consensus throughout. The earnings call had not happened when this was written.
Today at a glance:
- The beat: comparable EPS $0.91 against $0.88; revenue $13.38 billion against $12.92 billion.
- Volume: unit case volume +5%, led by India, China, Mexico and Brazil. North America was flat.
- Guidance: 2026 comparable EPS growth of at least 11%, up from 9% to 10% in July.
Coca-Cola's quarter: revenue +7% Y/Y, comparable EPS 3% above consensus
The third quarter of 2026 ended on October 2. All growth rates are against the third quarter of 2025 unless marked Q/Q.
- Net revenues +7% Y/Y to $13.38 billion, against $12.92 billion at FMP ($0.46 billion beat). Flat Q/Q.
- Organic revenues (non-GAAP, which strips out currency and acquisitions) +7%, after +6% in the second quarter.
- Operating income +12% Y/Y to $4.47 billion (−4% Q/Q). Comparable operating margin 32.9%, +1.0pp Y/Y and down from 35.6% in the second quarter.
- Diluted EPS $0.93, +8% Y/Y (−10% Q/Q from $1.03).
- Comparable EPS $0.91, +11% Y/Y, against $0.88 at FMP ($0.03 beat). In the second quarter it was $0.97, so −6% Q/Q.
- Free cash flow (non-GAAP) $11.4 billion for the first nine months.
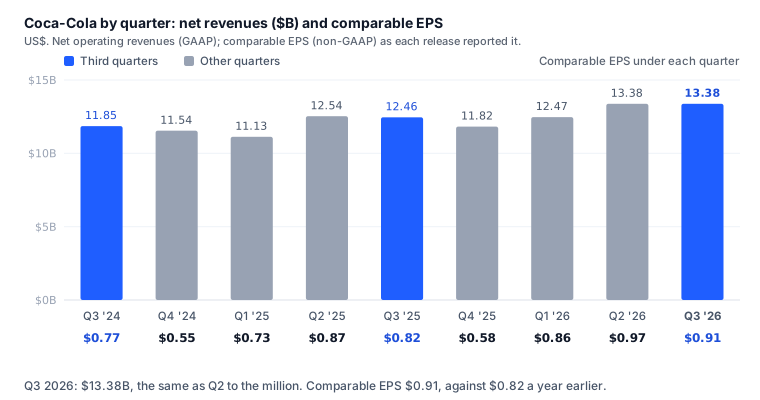
The second quarter is usually Coca-Cola's strongest. In 2025, comparable EPS also fell from $0.87 in the second quarter to $0.82 in the third.
Key developments:
- Concentrate ran ahead of drinks. Concentrate sales grew 7% and unit case volume 5%. Coca-Cola books revenue when it ships concentrate to bottlers, while volume counts the cases those bottlers sell. The release puts the 2-point gap down to the timing of shipments. In the second quarter it ran the other way: concentrate 1 point behind volume.
- Price/mix added 1%, half of the second quarter's 2%. Pricing went up; the mix of products and markets pulled it back down.
- Coca-Cola Zero Sugar grew 16%. Trademark Coca-Cola grew 5% and Diet Coke 6%. Sports drinks fell 3%, on a decline in Asia Pacific.
- Currency helped. It added 2 points to EPS growth. Comparable currency-neutral EPS grew 9%.
- GAAP and comparable EPS moved apart by tax items. The GAAP figure carried a $172 million benefit from tax matters this quarter and $442 million a year ago, which is part of why GAAP EPS grew 8% and comparable EPS 11%.
- Takeaways: revenue grew 7%, of which about 2 points was shipment timing. Comparable EPS grew 11%, of which 2 points was currency.
Volume by segment: North America flat, Latin America +6%
Four of the five segments sold more cases than a year earlier. The fifth was North America.
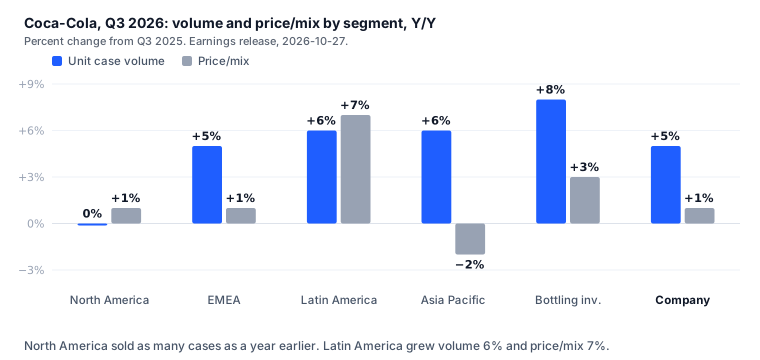
- North America: volume flat, price/mix +1%, operating income +5%. Trademark Coca-Cola grew; water, sports, coffee and tea declined. The company still gained value share there.
- Latin America: volume +6% and price/mix +7%. Operating income rose 29%, or 14% before currency and one-off items. Mexico's 100-year campaign is credited with part of the volume.
- Asia Pacific: volume +6%, but price/mix −2% from an unfavorable mix. Comparable currency-neutral operating income +14%.
- EMEA: volume +5%. Value share fell, with losses in France and the United Kingdom larger than gains in Nigeria and Morocco.
- Bottling Investments: operating income +261% to $205 million, on 8% more volume in India and South Africa.
2026 guidance: comparable EPS growth of at least 11%
Every line of the full-year outlook moved up from July.
| Measure | July guide | October guide |
|---|---|---|
| Organic revenue growth | about 5% | at least 5% |
| Comparable currency-neutral EPS growth, ex acquisitions and divestitures | 7% to 8% | at least 9% |
| Comparable EPS growth | 9% to 10% | at least 11% |
| Free cash flow | about $12.4B | at least $13.0B |
The comparable EPS line works out to a dollar figure. Coca-Cola's 2025 comparable EPS was $3.00, so at least 11% means at least $3.33 for 2026. The first nine months add up to $2.74 ($0.86 + $0.97 + $0.91). That leaves $0.59 or more for the fourth quarter, against $0.58 in the fourth quarter of 2025.
The fourth quarter has two things against it. It has six fewer days than the fourth quarter of 2025. And the sale of the bottling operations in Africa, which the company expects to close in the quarter pending regulators, takes about 4% off comparable revenue and 3% off comparable EPS. For 2027 the release puts the revenue headwind from that sale at about 8%; full guidance comes with the fourth-quarter report.
The stock: 3% below its 52-week high
KO closed at $92.70 on October 26, 2.8% below its 52-week high of $95.37. At 7:07 a.m. ET on October 27 it was bid at $94.00 before the open, 1.4% higher.
Our model puts the value at $53.77 a share, so on the October 26 close the stock is overvalued by 72% vs model. The models on the stock page range from $30.55 to $130.45.
Volume grew 5% in both the second and third quarters, and the guide now asks only $0.59 of the fourth. The open question is what North America does with a flat quarter behind it.
Sources and data
- The Coca-Cola Company, third quarter 2026 earnings release, 8-K exhibit 99.1, filed 2026-10-27.
- The Coca-Cola Company, second quarter 2026 earnings release, filed 2026-07-28: Q2 figures and the July guidance.
- The Coca-Cola Company, fourth quarter 2025 earnings release, filed 2026-02-10: 2025 comparable EPS of $3.00.
- Consensus estimates ($0.881 EPS, $12.92 billion revenue) and the October 27 pre-market quote: Financial Modeling Prep, read 2026-10-27.
- Model value and range: SweetValueLab, KO, snapshot of 2026-10-27.
The weekly
The week's 13F filings, insider trades and earnings, plus new research on the site. One email a week, no account.
More posts
- Alphabet Q3 2026: Cloud +103%, free cash flow −$9.1B
- GE Vernova Q3 2026: $29B of orders, paid for in advance
- SoFi Q3 2026: revenue +44%, a $0.90 EPS outlook for 2027
- Anthropic's S-1: a $974 million operating profit in Q2 2026
- Tesla–SpaceX merger: the exchange ratio, valued part by part
- SpaceX Q3 2026: revenue +161%, the valuation moves $2
- Why do stocks fall after beating earnings?
- Why Goldman, Citi, J&J and ASML stocks fell after earnings
- Anthropic's $16.8B quarter: the investor day numbers
- What is a DCF? What a corner shop is worth
- How the 10-year Treasury moves every valuation on this site
- Delta vs United by the numbers
- Anthropic's IPO prospectus: the numbers behind the $42B loss
- Who actually owns this stock: how to read a 13F
- How to read a market sentiment gauge
- Market breadth: the index can rise while most stocks fall
- How we value a stock: twelve models, one number
- Where the numbers come from: filings, point in time
- Tesla, taken apart: a sum of the parts in three scenarios
- How to read a reverse DCF: the growth a stock price implies
- How to value a bank: P/TBV, ROTCE and the line
- How to value a REIT: FFO, P/FFO and the yield spread
- How to value a software company: Rule of 40 and SBC
- Total return vs price return: what a stock chart leaves out
- What a backtest cannot tell you