Anthropic's $16.8B quarter: the investor day numbers
 Allen Yan · · 10 min read
Contents
This is the second post tracking Anthropic's IPO. The first, the numbers behind the $42B loss, laid out the confidential prospectus as Reuters read it on September 28 and 29: 2024 and 2025, the $518 billion of compute commitments and the Founder LLC. Those numbers have not changed. What changed is that the company has now shown outsiders a third quarter of 2026.
On Wednesday, October 14, Anthropic held an investor day for invited institutions at its San Francisco headquarters. Dario Amodei and the chief financial officer, Krishna Rao, presented. Nothing was filed and nothing was published. Everything below comes from people in the room, as Reuters (two attendees, by Milana Vinn and Krystal Hu), the Financial Times, Bloomberg and the Wall Street Journal reported it on October 14 and 15. Attendees were handed caps, some reading "thinking".
The labels follow the last post's, with one added (Attendees) and one renamed (the last post's Reuters is Prospectus here):
- Attendees: what people at the meeting told Reuters, the FT, Bloomberg or the WSJ.
- Prospectus: the confidential S-1 as Reuters quoted it in September.
- Other: other reporting, including what Anthropic has said in public, and estimates by outside analysts.
- Derived: our own arithmetic on the reported numbers.
All amounts are US dollars.
What changed since September 29
| Item | In the September 29 post | After the investor day | Source |
|---|---|---|---|
| Q1 2026 revenue | $4.73B | $4.7B | Attendees |
| Q2 2026 revenue | more than $11.5B | $11.6B ($11.5B in the FT's account) | Attendees |
| Q3 2026 revenue | not reported | $16.8B | Attendees |
| Adjusted profit | Q2 positive; FT expected Q3 too | Q3 positive, the second quarter in a row | Attendees (FT) |
| Adjusted operating margin | not reported | 11%; whether for Q3 or the year to date is disputed | Attendees |
| Cash flow | not reported | positive in Q3 | Attendees (FT) |
| Revenue per $1 of compute | not reported | $1.70 in Q3 | Attendees (FT) |
| Valuation | $965B in May, IPO target above $2T | prospective investors put fair value at $1.8T to $2T | Attendees (Bloomberg) |
| Timing | IPO this autumn | marketing from the week of November 9, trading before Thanksgiving (November 26), year-end at the latest | Other (Bloomberg) |
The prospectus figures for 2024 and 2025 stand as they were: $4.59 billion of revenue in 2025, an $8.06 billion operating loss, a $41.97 billion net loss.
Quarterly revenue: from ×2.47 to ×1.45 a quarter
Revenue went from $4.7 billion in the first quarter to $11.6 billion in the second and $16.8 billion in the third. The first step multiplied revenue by 2.47. The second multiplied it by 1.45. That is the 45% every headline quoted. Of the year's two steps, it is the slower one by a wide margin.
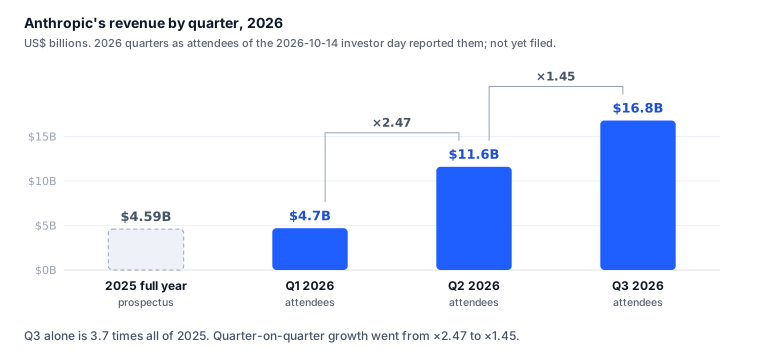
Two comparisons put the size in context. The third quarter alone is 3.7 times the $4.59 billion of all of 2025. The first nine months add up to $33.1 billion, 7.2 times that year.
Year on year, the second quarter is about 14.7 times the $0.787 billion of the same quarter of 2025, the one 2025 quarter the prospectus coverage gave. The third quarter has no 2025 figure to compare with yet.
The FT reported that the slowdown came in below what some investors had expected. Over the summer, several of them had told it the company would far exceed $100 billion of annualized revenue by December.
Run-rate: a month's revenue times twelve
The run-rate figures in the press and the quarterly figures are two different measurements, and mixing them produces most of the confusion about this company.
A run-rate takes one recent stretch of revenue and multiplies it up to a year. A month's revenue times 12 is the usual version. It says how big the business is right now. A quarterly figure says how much it actually took in over three months. When revenue grows every month, the run-rate at the end of a quarter is always higher than the quarter times four, because the last month is the largest.
Here are the annual figures in circulation, side by side:
| Figure | US$ billions | What it is | Source |
|---|---|---|---|
| Run-rate, end of July | 65 | one recent period, annualized | Other (Anthropic, via CNBC and Reuters, August) |
| Q3 × 4 | 67.2 | the quarter's average, annualized | Derived |
| Projected run-rate | about 74 | an outside estimate | Other (SemiAnalysis, via the FT) |
| Year-end run-rate | about 110 | what investors expect for December | Attendees (WSJ) |
Anthropic did not give an annualized number for the quarter.
The $110 billion is the most quoted number from the meeting and the least confirmed. The WSJ wrote that investors expect it. Reuters attributed it to analysts who had met the company.
What $110B by December would take
The $110 billion can be tested against the quarterly numbers with one assumption: revenue grows at a steady rate from month to month.
The steps:
- A quarter that is ×1.45 the one before means monthly growth of about 13.1%, because 1.131 × 1.131 × 1.131 = 1.45.
- Spread Q3's $16.8 billion over July, August and September at that rate. July comes out at about $4.9 billion, August $5.6 billion, September $6.3 billion.
- Each month times 12 gives that month's run-rate: about $59 billion for July and $76 billion for September.
- Keep the same 13.1% for October, November and December. December comes out at about $9.1 billion, a run-rate of about $110 billion.
So the $110 billion is what the third quarter's pace gives if it continues for three more months. The fourth quarter would have to grow by 45% again, to about $24.3 billion, after ×2.47 and then ×1.45.
This fit has one problem. Its July comes out at $59 billion, and in August Anthropic said July's run-rate was $65 billion. A second fit starts from the reported July instead:
- $65 billion ÷ 12 puts July's revenue at about $5.42 billion.
- That leaves $16.8 − 5.42 = $11.38 billion for August and September together.
- Call the month-to-month multiplier g (1.131 in the first fit), so August is 5.42 × g and September 5.42 × g². The three months must add up to Q3: 5.42 × (1 + g + g²) = 16.8, so 1 + g + g² = 3.10 and g = 1.033. That is about 3.3% a month.
- September's run-rate comes out at about $69 billion. Carried on at 3.3% a month, December is about $77 billion, and the fourth quarter about $18.5 billion, ×1.10 on the third.
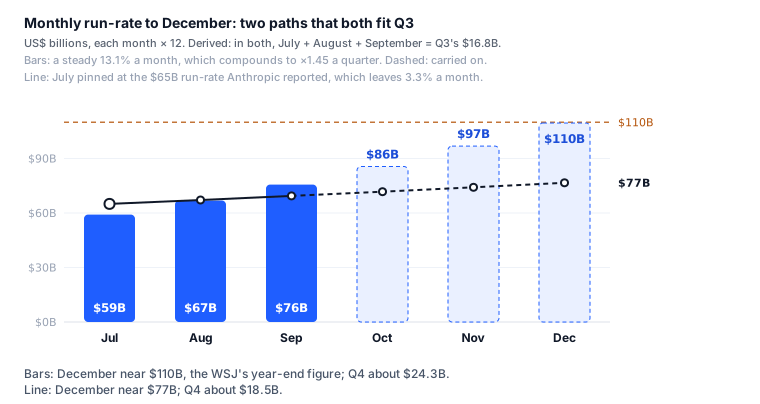
Both fits match the reported quarter exactly. They differ in when the growth happened. The first has revenue rising steadily through the quarter. The second takes the reported July as given, which puts most of the rise over the second quarter before July and leaves August and September adding little.
Neither is a forecast. The second depends on the $65 billion meaning what this post means by a run-rate, one calendar month times 12. If it was taken from the last weeks of July, July's real revenue was lower, more growth falls in August and September, and the second path is too low. SemiAnalysis's projected $74 billion sits between the two Septembers, $69 billion and $76 billion.
Adjusted operating margin, what "profitable" means here
"Profitable on an adjusted basis" is the phrase every report used. Behind it is one reported number: an adjusted operating margin of 11%.
An operating margin is operating profit divided by revenue. "Adjusted" means some expenses were taken out before the division. The reports agree that stock-based compensation is one of them. Anthropic has not said what else.
Two readings of the 11% are in circulation:
- Bloomberg reported an adjusted operating margin of more than 11% for the third quarter. On $16.8 billion that is about $1.85 billion.
- The Information reported 11% for the year through the third quarter. On the nine months' $33.1 billion that is about $3.6 billion.
For comparison, the prospectus showed an operating loss of $8.06 billion for 2025, on GAAP, with stock-based compensation included.
Adjusted operating income also stops above the line that produced most of the 2025 loss. That line was the $33.9 billion of non-operating items, mostly fair-value changes on financing instruments that may convert into shares. The previous post explained how it works: when the private valuation rises, the instruments are worth more and the change is booked as a loss. Between May and the IPO the price discussed went from $965 billion to as much as $2 trillion. If any such instruments were still outstanding in 2026, a GAAP net loss could sit beside an adjusted operating profit. That is an inference; the 2026 statements have not been reported.
Revenue per dollar of compute: $0.15, $0.63, $1.70
The FT reported a second number from the meeting: in the third quarter Anthropic took in $1.70 of revenue for every dollar spent on computing power.
The prospectus allows the same ratio for the two earlier years. In 2025 revenue was $4.59 billion and compute and infrastructure cost $7.33 billion, so each dollar of compute brought in about $0.63. In 2024 the figures were $0.386 billion of revenue and about $2.5 billion of compute (derived in the previous post), about $0.15.
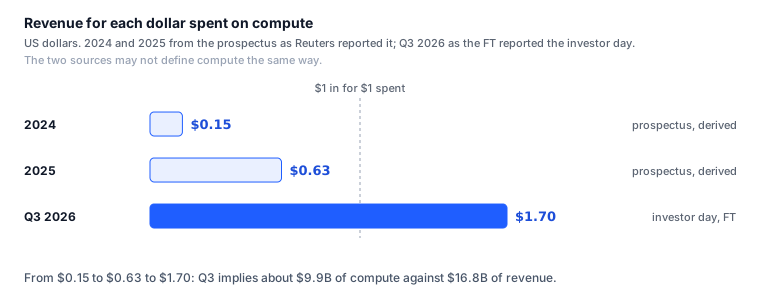
The caveat is the definition. The prospectus line was "compute and infrastructure" among operating expenses. The FT's phrase was "spent on computing power", and the reports do not say whether it covers training new models or only serving the existing ones. If the two measure different things, the three bars are not strictly comparable.
Taken at face value, $1.70 means compute cost about $9.9 billion in the third quarter, 59% of revenue. That is roughly $39.5 billion a year. For scale, the three commitments in the prospectus whose terms were reported (Google $111.1 billion, Amazon $110 billion, Microsoft $31.4 billion) average out to about $31.2 billion a year if spread evenly over their terms.
The third quarter's pace is already above that even spread, and Microsoft's contract only starts in November 2026. The spread also leaves out Broadcom and xAI, whose terms were not reported. So either the contracts are drawn down faster in their early years than an even spread assumes, or much of today's compute is bought outside them. The reports do not say which.
The multiple a $2 trillion price implies, updated
The previous post divided $2 trillion by each revenue figure then available. With the third quarter in, the table moves:
| Revenue base | US$ billions | $2T ÷ revenue | $1.8T ÷ revenue |
|---|---|---|---|
| 2025 reported | 4.59 | about 436× | about 392× |
| First nine months of 2026, annualized | 44.1 | about 45× | about 41× |
| Q3 2026 × 4 | 67.2 | about 30× | about 27× |
| SemiAnalysis projection | 74 | about 27× | about 24× |
| Year-end run-rate, as investors expect | 110 | about 18× | about 16× |
These are valuation over revenue. Net cash at the IPO is still unknown, so an enterprise value cannot be computed. In the previous post, the software board had a median EV/Revenue of 11.2× on the 2026-09-25 close, with Palantir highest at 77.7×. Those are the September readings and have not been refreshed here.
Every row except the first divides by a number that has not been filed.
What the meeting did not settle
- Gross or net revenue. The previous post asked whether 2025 revenue was $4.6 billion or the "about $10 billion" CNBC reported in August, and pointed at revenue sold through cloud partners. None of the October reports addresses it.
- Q2: $11.5 billion or $11.6 billion. The FT says $11.5 billion, Reuters and CNBC $11.6 billion.
- The 11% margin's period. Q3 alone (Bloomberg) or the year to date (The Information).
- What "adjusted" removes. Stock-based compensation, by the reports. Anything else is not known.
- The $110 billion. An investor and analyst expectation, never presented as company guidance.
Next update: the public S-1
SEC rules require the S-1 to be public at least 15 days before the roadshow. If marketing starts the week of November 9, it is due by about October 25. When it is on EDGAR, both posts get a dated update with the filed numbers.
Sources
- Reuters, At Anthropic pre-IPO meet: 'Thinking' caps, surging revenue, no human extinction (via TradingView, October 14) and Anthropic's Q3 revenue surges 45% to nearly $17 billion (via Investing.com)
- Financial Times, as summarized in Anthropic tells investors Q3 revenue jumped 45% to nearly $17 bln (Yahoo Finance)
- Bloomberg, Anthropic Revenue Hits $16.8 Billion in Third Quarter and Anthropic Is Said to Plan Pre-IPO Investor Day as Listing Nears
- CNBC, Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO, relaying the WSJ's $110 billion
- The Information, Anthropic's rapid but slowing growth could weigh on IPO valuation (paywalled), on the 11% margin for the year through Q3, as relayed by The Decoder, Anthropic's Q3 revenue hits $16.8B but growth slows; Quartz, on the adjusted profit
- Implicator, on the $110 billion being the least confirmed figure
- PYMNTS, Anthropic targets pre-Thanksgiving IPO at $2 trillion valuation
- Run-rate history: CNBC, annualized revenue run rate climbed to $65 billion in July
- 2024 and 2025: the previous post and its Reuters sources
The weekly
The week's 13F filings, insider trades and earnings, plus new research on the site. One email a week, no account.
More posts
- What is a DCF? What a corner shop is worth
- How the 10-year Treasury moves every valuation on this site
- Delta vs United by the numbers
- Anthropic's IPO prospectus: the numbers behind the $42B loss
- Who actually owns this stock: how to read a 13F
- How to read a market sentiment gauge
- Market breadth: the index can rise while most stocks fall
- How we value a stock: twelve models, one number
- Where the numbers come from: filings, point in time
- Tesla, taken apart: a sum of the parts in three scenarios
- How to read a reverse DCF: the growth a stock price implies
- How to value a bank: P/TBV, ROTCE and the line
- How to value a REIT: FFO, P/FFO and the yield spread
- How to value a software company: Rule of 40 and SBC
- Total return vs price return: what a stock chart leaves out
- What a backtest cannot tell you