SoFi Q3 2026: revenue +44%, a $0.90 EPS outlook for 2027
 Allen Yan · · 5 min read
Contents
SoFi Technologies reported its third quarter of 2026 before the open on October 27. Adjusted net revenue grew 44%, members grew 35%, and the company gave a 2027 outlook for the first time. CEO Anthony Noto called the quarter "even more remarkable given how 2026 has unfolded". By the October 26 close the stock was down 45% for the year.
Everything below comes from the earnings release (8-K exhibit, filed 2026-10-27). I use FMP's consensus throughout; the release compares its guidance with FactSet's. The earnings webcast started at 8:00 a.m. ET, after this was written.
Today at a glance:
- The beat: adjusted EPS $0.18 against $0.16; adjusted net revenue $1.37 billion against $1.25 billion.
- Lending: record originations of $16.9 billion, +71% Y/Y.
- Loan marks: the premium SoFi carries its loans at over principal fell as benchmark rates rose.
- Guidance: 2026 revenue raised to about $5.04 billion; adjusted EPS of about $0.90 for 2027.
SoFi's quarter: adjusted net revenue +44% Y/Y, adjusted EPS 11% above consensus
The quarter ended September 30. Growth rates are against the third quarter of 2025 unless marked Q/Q.
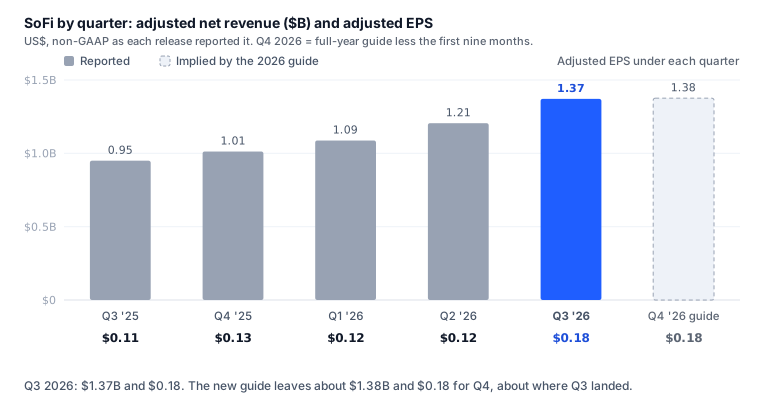
- Adjusted net revenue (non-GAAP) +44% Y/Y to $1.37 billion, against $1.25 billion at FMP ($116 million beat). +14% Q/Q.
- GAAP net revenue +44% to $1.39 billion.
- Adjusted EBITDA +70% to $470 million, a 34% margin. +31% Q/Q.
- Net income (GAAP) +73% to $241 million, and diluted EPS $0.18 against $0.11 a year ago and $0.12 in the second quarter.
- Adjusted EPS $0.18 against $0.16 at FMP ($0.1623, so a $0.02 beat).
- Members 17.1 million (+35%), with a record 1.2 million added in the quarter. Deposits rose $5.8 billion Q/Q to $51.3 billion.
- Tangible book value per share $7.48, from $5.97 a year ago and $7.34 at the end of June.
Key developments:
- Lending carried the quarter. Lending adjusted net revenue rose 68% to $807 million, 59% of the total. Personal loan originations were $12.6 billion, of which $3.6 billion was made for third parties through the Loan Platform Business. Student loan originations rose 96% to $2.9 billion. Origination fees rose 158%.
- Reported charge-offs fell. The personal loan charge-off rate was 2.26%, down 34 basis points from a year ago. Leaving out sales of late-stage delinquent loans, SoFi estimates it at about 3.4%, 30 basis points better than the second quarter.
- Financial Services products grew faster than its revenue. Products rose 44% to 23.2 million and revenue 25% to $525 million. Revenue per product was $90, against $104 a year earlier and $88 in the second quarter. The segment's contribution margin fell to 50% from 54%.
- Technology Platform revenue fell 24% to $87 million, after a large client left before the end of 2025. Without that client it grew 18%.
- Takeaways: revenue grew 14% in one quarter, and most of the growth was lending. The net interest margin was 6.14%, up 16 basis points from the second quarter.
Loan marks: higher benchmark rates, a smaller premium over principal
SoFi carries its personal, student and home loans at fair value, so a change in interest rates changes what its loans are worth on the balance sheet. The benchmark rates in its valuation model rose sharply in the quarter: two-year SOFR from 3.99% to 4.75% for personal loans, four-year SOFR from 3.90% to 4.80% for student loans.
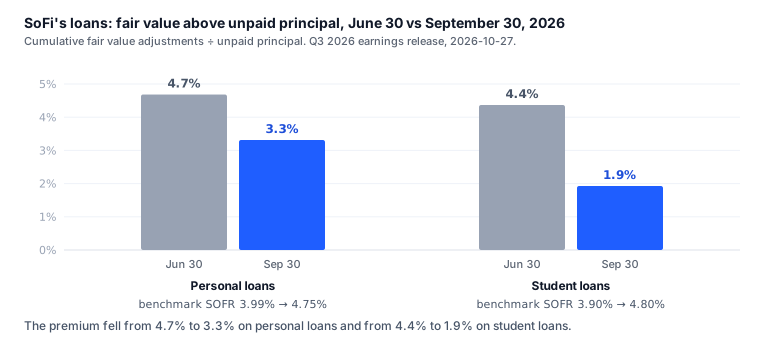
In dollars, the cumulative fair value adjustments on the two books went from $1.93 billion to $1.37 billion, $555 million less. That figure also moves with loans sold, paid down and newly made, and the release does not say how much of it passed through revenue in the quarter.
The default rate the model assumes for personal loans rose to 5.10% from 4.77%, and for student loans to 0.89% from 0.73%. In the same quarter, the charge-off rates it reported came down.
Guidance: 2026 revenue raised to $5.04 billion, 2027 EPS of $0.90
| Measure | July guide | October guide |
|---|---|---|
| 2026 adjusted net revenue | $4.75B to $4.85B | about $5.04B |
| 2026 adjusted EBITDA | about $1.6B | about $1.66B |
| 2026 adjusted net income | about $825M | about $840M |
| 2026 adjusted EPS | about $0.60 | about $0.61 |
| 2027 adjusted EPS | none | about $0.90 |
The October release says SoFi "continues to expect" about $840 million of adjusted net income. The July release said about $825 million.
The full-year figures leave a fourth quarter close to the third. Adjusted net revenue of $5.04 billion less $3.66 billion in the first nine months is about $1.38 billion, against $1.37 billion in the third quarter. Adjusted EPS of $0.61 less $0.43 is about $0.18, the same as the third quarter.
For 2027 SoFi expects about $6.4 billion of adjusted net revenue (+27%), $2.24 billion of adjusted EBITDA and $1.28 billion of adjusted net income. The release says all of these are above FactSet's estimates as of October 26.
The stock: down 45% in 2026
SOFI closed at $14.46 on October 26, 45% below its $26.18 close at the end of 2025 and 56% below its 52-week high of $32.73. At 7:43 a.m. ET on October 27 it was bid at $15.61 before the open, 8.0% higher.
SoFi is not among the 518 stocks this site values, so there is no model figure here.
SoFi has come in above FMP's revenue consensus in each of the ten quarters FMP lists, back to mid-2024. The next check on the guide is the fourth quarter, reported in early 2027.
Sources and data
- SoFi Technologies, third quarter 2026 earnings release, 8-K exhibit 99.1, filed 2026-10-27.
- SoFi Technologies, second quarter 2026 earnings release, filed 2026-07-29: Q2 figures and the July guidance.
- SoFi Technologies, first quarter 2026 and fourth quarter 2025 earnings releases: the quarterly figures in the chart.
- Consensus estimates ($0.1623 adjusted EPS, $1.255 billion adjusted net revenue), closing prices and the October 27 pre-market quote: Financial Modeling Prep, read 2026-10-27.
The weekly
The week's 13F filings, insider trades and earnings, plus new research on the site. One email a week, no account.
More posts
- Alphabet Q3 2026: Cloud +103%, free cash flow −$9.1B
- GE Vernova Q3 2026: $29B of orders, paid for in advance
- Coca-Cola Q3 2026: volume +5%, EPS guidance raised to 11%
- Anthropic's S-1: a $974 million operating profit in Q2 2026
- Tesla–SpaceX merger: the exchange ratio, valued part by part
- SpaceX Q3 2026: revenue +161%, the valuation moves $2
- Why do stocks fall after beating earnings?
- Why Goldman, Citi, J&J and ASML stocks fell after earnings
- Anthropic's $16.8B quarter: the investor day numbers
- What is a DCF? What a corner shop is worth
- How the 10-year Treasury moves every valuation on this site
- Delta vs United by the numbers
- Anthropic's IPO prospectus: the numbers behind the $42B loss
- Who actually owns this stock: how to read a 13F
- How to read a market sentiment gauge
- Market breadth: the index can rise while most stocks fall
- How we value a stock: twelve models, one number
- Where the numbers come from: filings, point in time
- Tesla, taken apart: a sum of the parts in three scenarios
- How to read a reverse DCF: the growth a stock price implies
- How to value a bank: P/TBV, ROTCE and the line
- How to value a REIT: FFO, P/FFO and the yield spread
- How to value a software company: Rule of 40 and SBC
- Total return vs price return: what a stock chart leaves out
- What a backtest cannot tell you